Selling your business: What happens to your employees’ contracts, and what do you tell them?
When you sell, your employees’ contracts stay, with their pay and seniority. What to tell them, when, and the one promise you can’t make: the boss.
“If I sell, my people lose their jobs. The buyer will keep whoever he wants.” I hear some version of this in nearly every first conversation about a sale, said quietly, as the reason to wait another year.
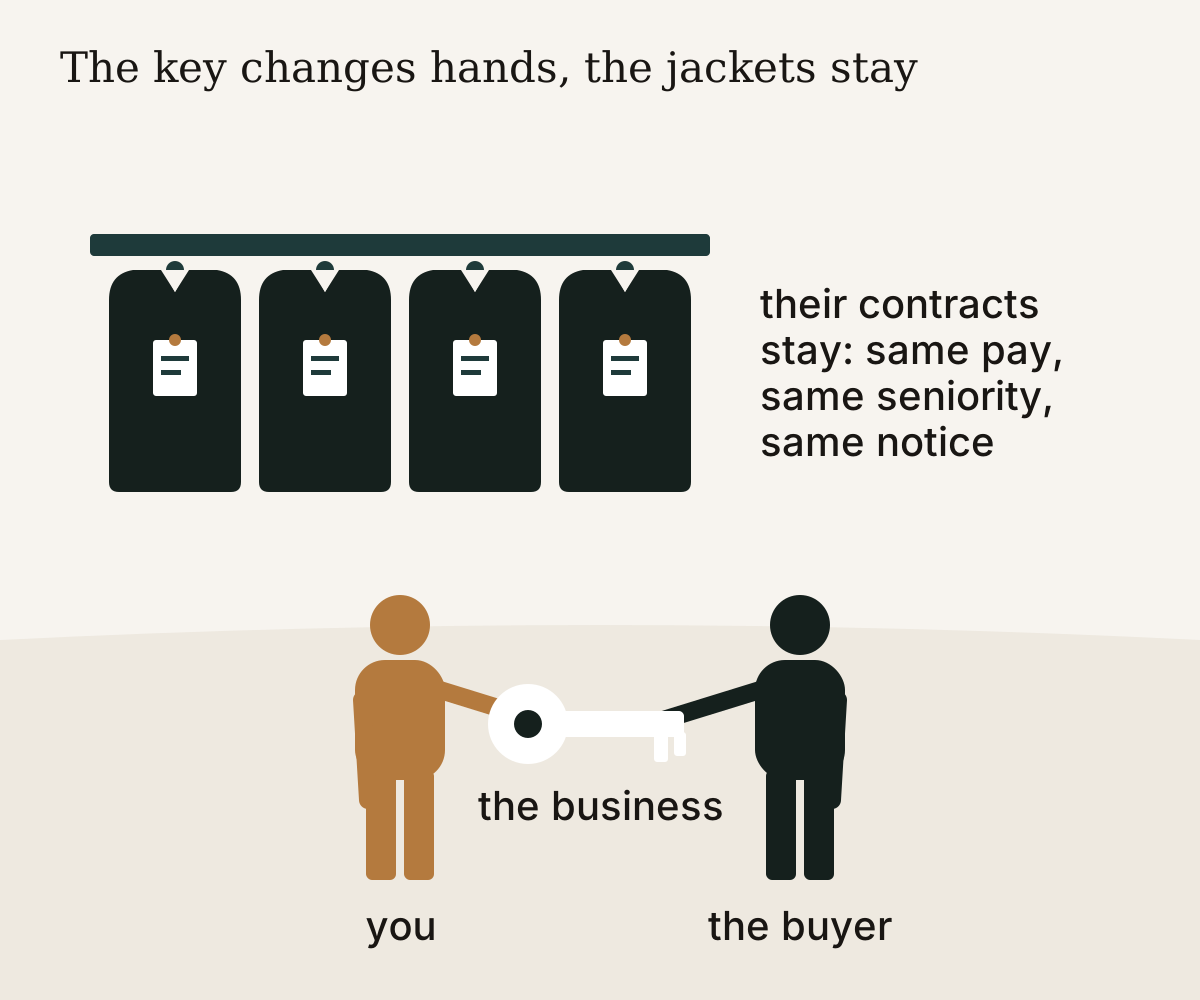
The contracts stay. If you sell the company’s shares (a share deal), the employer doesn’t change: the same company employs the same people on the same terms, and only its owner is new. If you sell the business itself, asset by asset (an asset deal), the employment contracts cross to the buyer with their terms. In Switzerland, Germany and Austria, for example, the law says so. Elsewhere, ask your lawyer whether the contracts follow the business where you are. In those same three countries, the staff, or those who speak for them, must also be told before the business changes hands. Elsewhere, that is the second question for your lawyer: what do I tell my people, and when? What you can’t promise them is the boss.
“The buyer will keep whoever he wants”
The picture behind this one is a shop that shuts on Friday and reopens on Monday under a new sign, with a fresh round of interviews. When the business itself is sold, each contract goes across with what the employee has built up: the pay, the years of seniority, the notice period. Under those same laws, the buyer steps into the contract as it stands. The foreman who started as an apprentice twenty-two years ago doesn’t go back to zero on the day of the transfer. His twenty-two years go with him.
In a share deal, legally, nothing moves. Next month’s payslip carries the same company name as last month’s. The choice between the two routes matters for much else, and it’s worth weighing the two structures side by side before a buyer chooses for you.
One wrinkle. When the business changes employer, an employee can refuse to go across to the buyer. The conditions for refusing differ from one of those countries to the next, and so does what happens next, so the question for your lawyer is short: what would a refusal mean here? In Switzerland, for example, refusing doesn’t mean walking out that afternoon. The contract ends when the legal notice period runs out, and until then the employee works for the buyer.
“I can promise them nothing will change”
It comes naturally at the staff meeting, and from a good place. You can promise the contract. You can’t promise the boss, the way he runs things, or what the organisation looks like in two years. The buyer decides that; it’s part of what he’s paying for.
Take a made-up case, not a client: a plumbing and heating firm of 16 people, its owner 60, sold to a competitor from the next town. The new owner may merge the two stockrooms of fittings into one, move the service jobs onto his own scheduling system, and send the Tuesday crew to jobs on his side of town. The contracts say nothing about any of it. All of it changes a working day.
Where the law carries the contract across, it stops there. In Germany, for example, a dismissal because of the transfer, by the old owner or the new one, is void. A dismissal for some other reason remains possible.
So promise what you control: their contract crosses intact, and they’ll hear every step from you first. People remember the second promise longer than the first. For the two or three people the business can’t do without, you’ll want more than a promise, and keeping key people through the sale is work of its own.
“I’ll tell them after the signature, when it’s certain”
Why worry sixteen people over a deal that might still fall through? Two things get in the way.
The first is the law. When the business itself changes employer, in those same three countries, the staff, or those who speak for them, must be informed before the transfer: the reason for the sale and what it changes for them, and usually the date and the measures planned. The law asks for little in the way of form: a written notice is enough. In Austria, for example, a firm with no staff representatives can inform its people in writing by a notice posted where everyone can read it. A notice on the board between the shift schedule and the safety poster meets the rule. Your team will want to hear it from you.
The second is the rumour, which never waited for anyone’s signature. Unusual visits, a stranger in a good coat walking the stockroom with you on a Saturday, folders that leave the office in a box. In the plumbing firm, the apprentice spots the competitor’s van in the yard twice in a month. By the third time, the whole crew has drawn its own conclusion, and it’s usually darker than the truth.
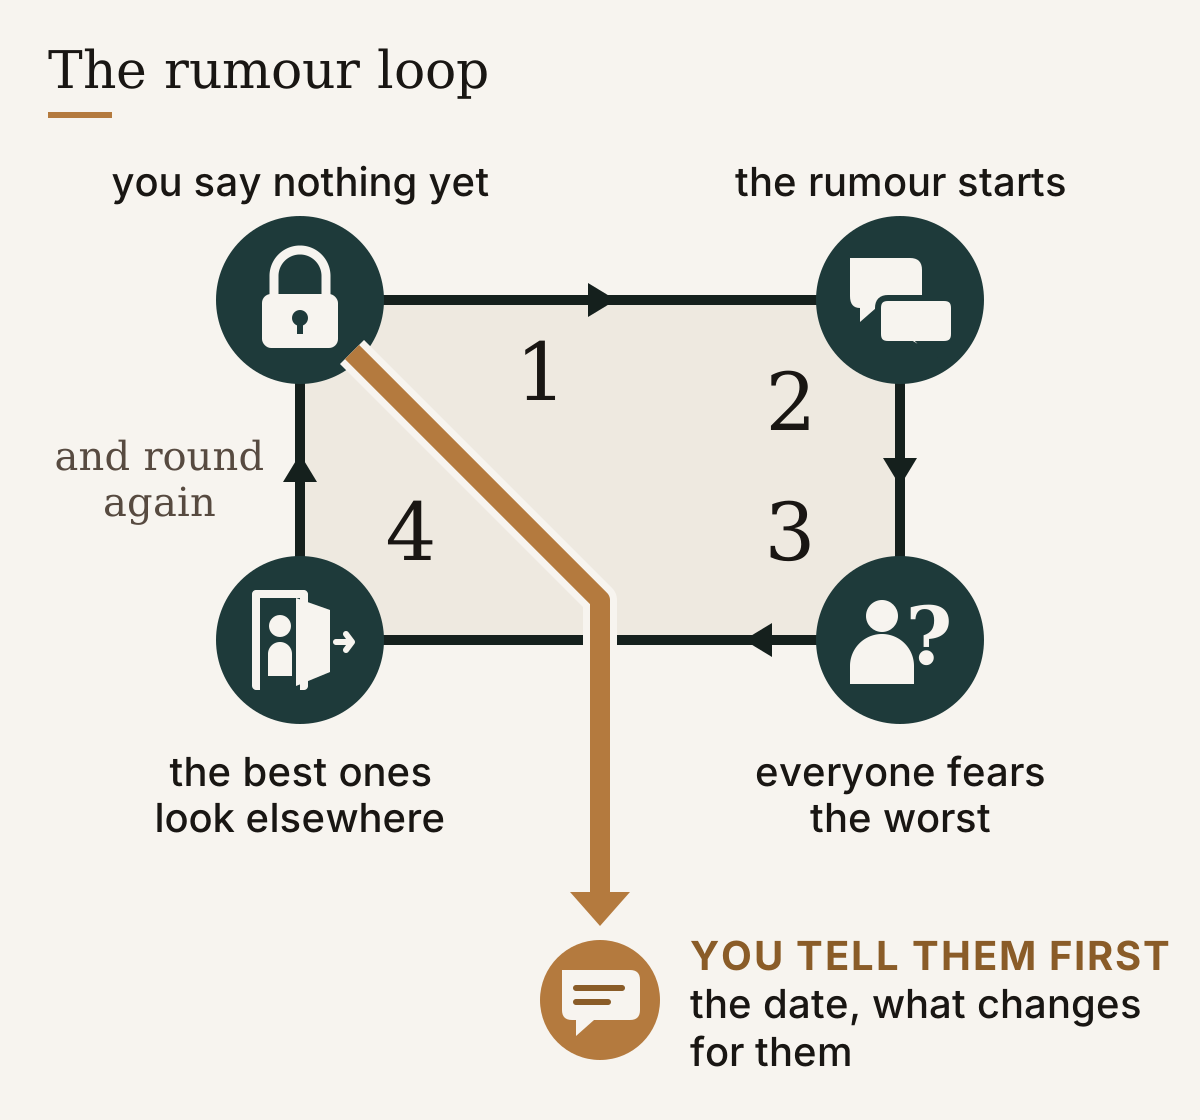
In the sales I steer, what drives the best people out is the silence and the uncertainty, far more than the sale itself. A key employee who hears it from you, with a date and what changes for him, most often stays. The buyer is watching too. One who senses a worried team, or hears that two key people are looking elsewhere, lowers his price or writes into the sale contract a condition that those people stay.
The timing that works runs in two rings. A small circle of key people learns early, under confidentiality, and who knows what, and when is decided in advance. Everyone else does hear it after the signature, but from you, and before the day of the transfer: “when it’s certain” can’t mean the day the buyer walks through the door.
Who in your firm would notice first that something’s going on? In the firms I see, it’s whoever answers the phone and takes messages from callers with names nobody recognises.
Sources
- Swiss Code of Obligations (CO), Art. 333 and 333aSwitzerlandFedlex (opens in a new tab)
- German Civil Code (Bürgerliches Gesetzbuch), § 613aGermanygesetze-im-internet.de (opens in a new tab)
- Austrian Employment Contract Law Adaptation Act (Arbeitsvertragsrechts-Anpassungsgesetz), §§ 3 and 3aAustriaRIS (opens in a new tab)
End of the article.


